US equities came under pressure this week, led by a sharp sell-off in technology and AI-related stocks. The Nasdaq fell 5.5% on Thursday as the Democratic midterm sweep raised concerns over tighter regulation and the pace of US data-centre development, adding to existing worries around elevated AI capex and investment returns.
US data remained resilient, with payrolls rising by 165,000 in October and unemployment edging down to 4.1%, while JOLTS and ISM data also pointed to continued economic strength. In Europe, inflation rose while PMIs softened. On the central bank front, the Bank of England and Reserve Bank of Australia raised rates, while Brazil held steady and Mexico cut.
Last week's highlights
 |
- Nonfarm Payrolls and Unemployment Rate (06/11) - payrolls rose by 165,000 in October, well above the 59,000 expected, while unemployment edged down to 4.1% from 4.2%
- ISM Manufacturing PMI (02/11) Non-Manufacturing PMI (04/11) - remained expansionary with manufacturing rising to 55.5 while services eased slightly to 54.5.
- ADP Nonfarm Employment Change (04/11) - US private employers added 86,000 jobs in October, above expectations of roughly 69,000.
|
 |
- CPI and Core CPI (YoY) (04/11) - Headline inflation rose to 4.0% in October from 3.8%, while core CPI held at 2.5%, both in line with expectations.
- HCOB Eurozone Services and Composite PMI (04/11) - Services PMI fell to 51.4 from 53.0, while the Composite PMI declined to 51.7 from 53.1.
|
 |
- CPI (YoY) (04/11) - rose to 4.0% in October from 3.8% in September, in line with expectations, driven largely by higher energy prices.
- BoE Interest Rate Decision (05/11) - Raised Bank Rate by 25bps to 4.0% in an 8–1 vote, citing rising energy-driven inflation pressures and stronger-than-expected economic activity.
|
 |
- Brazil Interest Rate Decision (04/11) - held the Selic rate at 13.75%, unanimously pausing its rate-cutting cycle amid elevated inflation expectations and increased uncertainty following the election.
- China Manufacturing PMI (02/11) Services PMI (04/11) - Manufacturing PMI eased slightly to 52.0 from 52.1, while Services PMI fell to 50.8 from 51.6.
|
Looking ahead, focus turns to US CPI and PPI, alongside whether weakness in AI and technology stocks broadens into wider risk sentiment.
What's on the radar
|
- CPI – October (10/11)
- PPI – October (13/11)
- 3 Year Treasury Auction (9/11)
- 10 Year Treasury Auction (10/11)
- 30 Year Treasury Auction (12/11)
|
|
|
|
|
|
- China CPI and PPI (09/11)
- China Trade Data (10/11)
- India CPI (12/11)
- Brazil CPI (12/11)
|
Chart of the moment – Disinflation almost everywhere
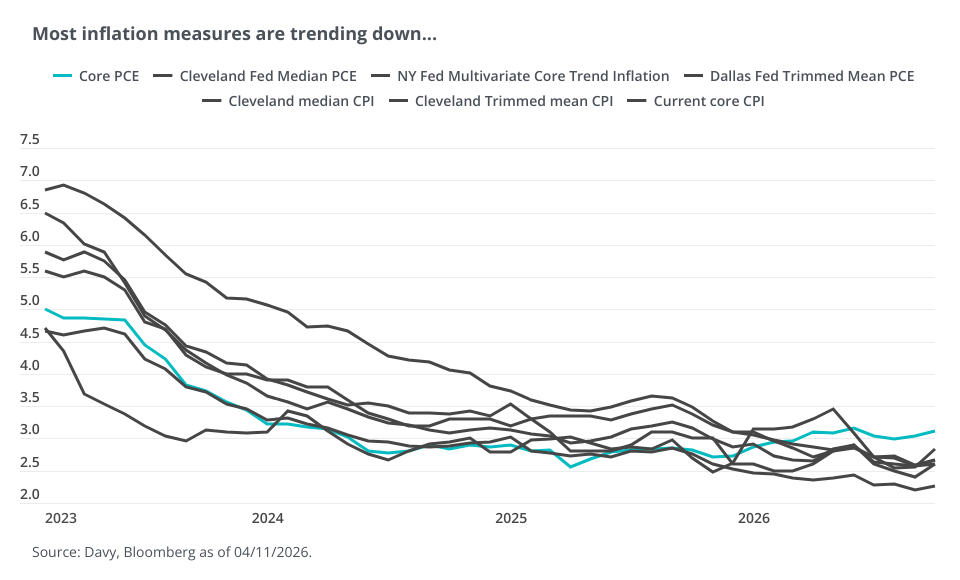
- Most alternative measures of core inflation continue to trend lower, with several now around 2.5%, suggesting broader price pressures are moderating.
- In contrast, core PCE has recently moved back above 3%, highlighting a divergence between the Fed’s preferred measure and wider underlying inflation indicators.
- Fed Chair Kevin Warsh has stated that PCE is the Fed’s preferred measure and that the 2% target remains firm, reinforcing the need for further progress on inflation.
- Markets still expect tighter policy over the next 12 months, although a meaningful slowdown in data-centre investment could weaken growth and the labour market enough to reduce the need for further hikes.