Global markets remained volatile this week as stronger inflation data pushed bond yields and the dollar higher. US headline CPI rose 0.4% in October, above expectations, while producer prices increased 0.3% and annual PPI accelerated to 6.5%. The data reinforced expectations that the Federal Reserve may need to raise rates further.
Technology stocks faced renewed pressure following Jensen Huang’s departure from Nvidia, adding uncertainty ahead of the company’s earnings next week. However, broader equity markets proved more resilient, recovering some of the losses from the previous week.
Elsewhere, economic activity remained firm. The UK economy grew 0.7% in Q3, supported by services and AI-related activity, while eurozone GDP expanded 0.4%. China’s exports also remained strong, pushing its year-to-date trade surplus above $1tn, although softer consumer inflation continued to highlight weak domestic demand.
Last week's highlights
 |
- CPI – October (10/11) - Headline inflation rose 0.4% MoM, easing from 0.6% in September but coming in above expectations, while core CPI rose 0.3% for a third consecutive month.
- PPI – October (13/11) - Rose 0.3% m/m in October, slightly below the 0.4% expected, while annual inflation accelerated to 6.5%.
- 10 Year Treasury Auction (10/11) - The $42bn sale also saw softer demand, stopping at 5.0%.
|
 |
- Q3 GDP (13/11) - GDP grew 0.4% q/q and 1.3% y/y in Q3.
|
 |
- Q3 GDP (12/11) - The UK economy grew 0.7% q/q in Q3, up from 0.5% in Q2 and in line with expectations, driven mainly by a 0.9% rise in services activity.
|
 |
- China CPI and PPI (09/11) - CPI rose 0.7% YoY, easing from 0.9% in September, while PPI inflation accelerated to 5.7% YoY, up from 5.0% previously.
- India CPI (12/11) - October inflation rose to 6.09% y/y from 5.54%, above the 5.93% consensus, as food inflation accelerated to 8.94%.
- Brazil CPI (12/11) - October inflation slowed to 0.14% m/m from 0.82%, below the 0.25% consensus, while annual inflation edged up to 4.63%.
|
Looking ahead, attention turns to Nvidia earnings, US retail sales and the FOMC minutes, alongside UK inflation and labour-market data.
What's on the radar
|
- Retail Sales (17/11)
- FOMC Meeting Minutes (18/11)
- Initial Jobless Claims (19/11)
|
|
|
|
- CPI – October (18/11)
- Labour Market data (17/11)
- Retail sales (20/11)
|
|
- China Industrial Production + Fixed Asset Investment (16/11)
- Japan National Core CPI (19/11)
|
Chart of the moment – Big Moves, partial reversals
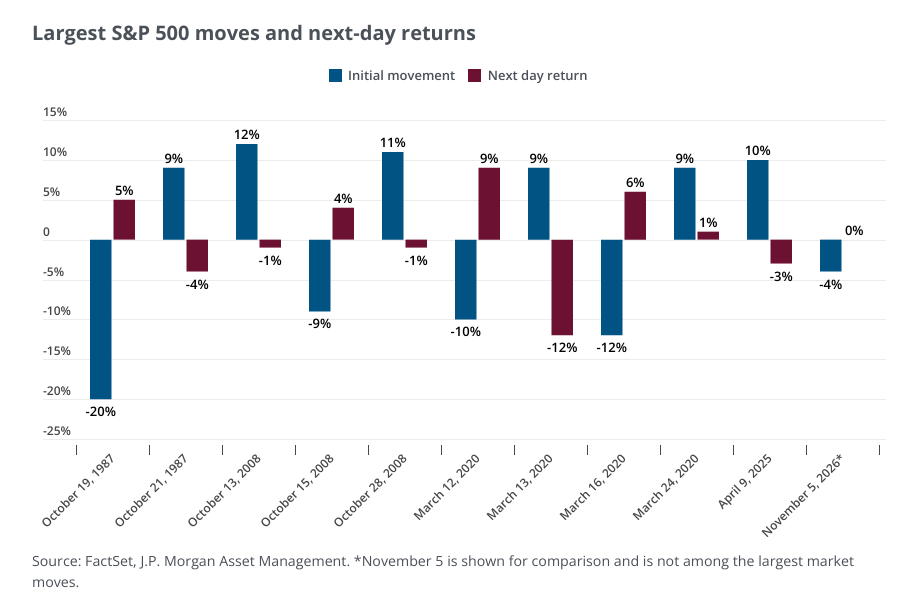
- Sharp S&P 500 moves have historically been followed by a partial reversal the next day.
- The 5th November decline, driven by the Democrats’ midterm win and concerns over tighter tech and AI regulation, was relatively modest compared with past extremes, while markets were broadly flat the following day.
- The biggest sell-offs shown were typically followed by sizeable rebounds, while the latest decline saw little follow-through either way.